While the corporate tax rate is often cited by the media when discussing tax matters, it does not give a complete picture of the taxes actually paid by you or your company. Low corporate tax rates in a country do not automatically mean that all tax obligations can be fulfilled in that country. Other taxes and requirements depend on the corporate form, the residences of management and employees, the existence of a permanent establishment, etc. Moreover, the owner’s tax situation as regards salary and dividend income in his/her country of tax residency must not be ignored.
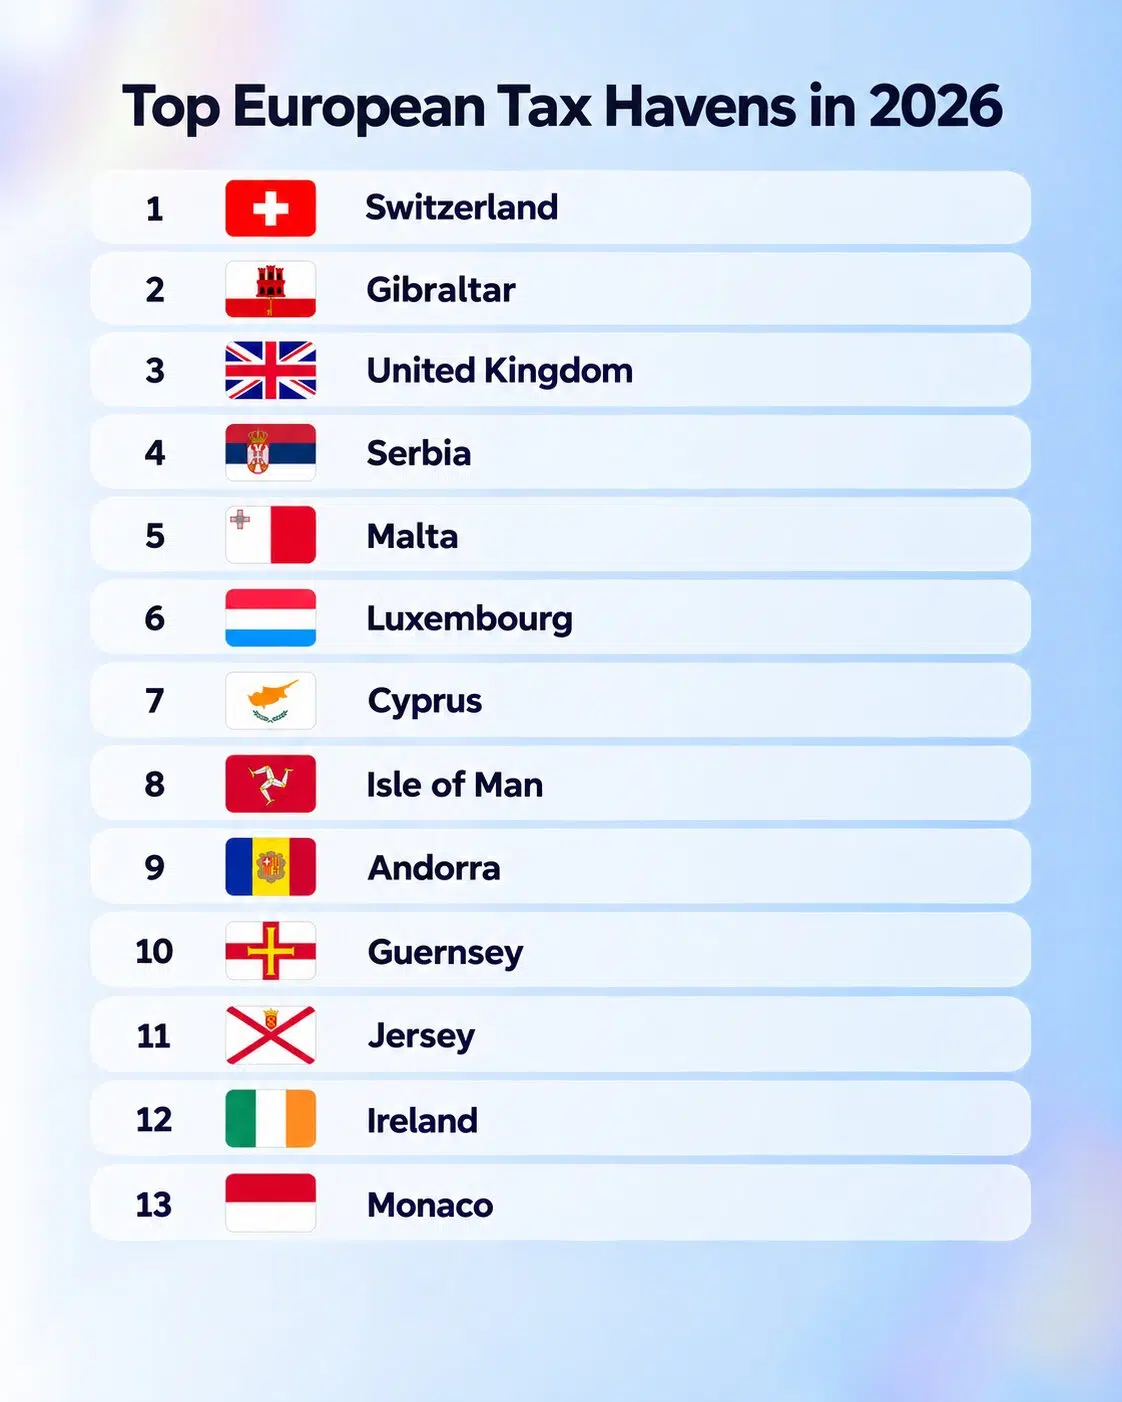
A great portion of tax planning is carried out in countries within Europe, and a guide to the most popular countries is set out below. Not all of these countries are considered ‘tax havens.’ Some have low standard rate corporate tax, but the tax relief is given subject to conditions, and furthermore, special treatment of certain income types as well as individual benefits for residents can apply. The two well-established locations of the UK and Luxembourg are therefore outlined in more detail below.
Our aim with this guide is to assist businesses in selecting countries best for their tax planning and to outline some key points that you must consider when setting up a new company or moving to a new country with the aim of paying less tax. These considerations will be specific to you and your proposed business and owner(s) and must be carefully weighed and calculated within the relevant country(ies).
What Does “Tax Haven” Mean in This Guide?
The term “tax haven” in this guide refers to countries and territories with low tax rates, conditional tax benefits, territorial taxation, specific special holding company structures and facilities, and favorable tax treatment of natural persons.
Three things need to be clearly distinguished:
- Zero corporate tax is not automatically introduced by so-called “tax havens” for income derived from financial services or real estate activities;
- A refund of withholding tax by a shareholder is only granted after the payment of the dividend by the company;
- Individual taxpayers only benefit from the tax advantages of a “tax haven” country if they are residents of that country.
What Actually Determines Your Tax Burden?
When assessing the tax obligations of your company, consideration must be given to the geographical location in which it trades, the country in which it is managed, and administered and the tax residence of its owners. Thus, a company incorporated in a country may also be subject to tax in another country where it has a permanent establishment (PE) and trading profits are taxed at comparable rates to other types of profit. However, different rates of tax may apply to capital gains, dividends, property income, etc. Further benefits can be obtained from trading from a particular location dependent upon issues such as local staffing and expenditure and the location of key decision makers.
Trade profits of a company are generally taxed at rates applicable for other types of income. In addition, different rates of tax may apply to capital gains, dividends, property income, etc. Benefits of setting up operations in a particular location will also depend on issues such as local staff, local expenditures, and where key decisions are taken.
Distributing profits in the form of dividends to the company owners could further be subject to taxes and social security charges, such as payroll taxes, dividend taxes, withholding taxes, and even employer’s social security contributions. The information provided above is extremely relevant when comparing different structures and their total annual costs.
How We Selected the Jurisdictions
The below locations have been reviewed against the original article and assessed on an equal footing with each other. Note that due to country-specific issues, it is not possible to establish a definitive ranking between jurisdictions.
- What is the overall corporate tax framework, and which special tax exemptions will apply to various types of income?
- Is this country of relevance to the individual considering a move?
- From where will the business be operated and managed, and where is the individual relocating to?
- What reporting and disclosure of ownership and substance requirements will such a structure have?
- For which types of businesses or investments would additional research be advisable?
- What potential problems are there to achieve tax-efficient solutions?
European Low-Tax Jurisdictions: Comparison Table
| Jurisdiction | Standard corporate tax | Potential effective rate / special regime | Personal income tax | EU / EEA status | Best suited for | Key limitation |
|---|---|---|---|---|---|---|
| Switzerland | Federal, cantonal and municipal taxes; combined rate varies by location | Location and qualifying reliefs can change the result; calculate for a specific canton and municipality | Federal and local rates vary | Neither | Business with Swiss operations; genuine relocation and wealth planning | No single Swiss corporate or personal rate |
| Gibraltar | 15% | Treatment depends on the source and nature of income; foreign ownership is not an automatic exemption | Depends on income and the applicable personal tax system | Neither | Business with a genuine Gibraltar connection | Income and management elsewhere may be taxable elsewhere |
| United Kingdom | 25% main rate; 19% small-profits rate, with marginal relief where applicable | Activity-specific reliefs may apply; company chargeable gains generally form part of corporation tax profits | Progressive; rates and bands differ for some Scottish income | Neither | Business genuinely operating in the UK | Company and owner tax must both be counted |
| Scottish limited partnership | No standalone universal corporate rate | Generally tax-transparent for relevant UK purposes; treatment depends on the partners and activity | Depends on each individual partner’s tax residence and income | UK: neither | Genuine partnership or joint venture | Transparency shifts the tax analysis to the partners; control disclosures apply |
| Serbia | 15% | Specific investment or R&D relief may apply if conditions are met | Depends on income type; employment contributions and possible annual tax also matter | Neither | Operating business with Serbian staff or activity | Payroll and cross-border payments can alter the overall result |
| Malta | 35% | Qualifying shareholders may claim a refund of company tax after a dividend distribution | Progressive, up to 35%; residence and domicile matter | EU | Structures able to meet and use the refund rules | Refund eligibility, timing and shareholder tax require separate calculations |
| Luxembourg | Corporate income tax plus municipal business tax and other applicable charges | Participation exemption may apply to qualifying holdings | Progressive; depends on income and personal circumstances | EU | Substantial holding or investment structure | Headline corporate tax alone understates cost and complexity |
| Cyprus | 15% from 1 January 2026 | Income-specific exemptions or reliefs require separate eligibility checks | Progressive, up to 35%; residence and income type matter | EU | Operating or holding structure with Cyprus substance; genuine relocation | The former 12.5% corporate rate is outdated |
| Isle of Man | 0% general company rate | Higher rates for specified income; minimum-tax top-up for in-scope groups | 10% standard and 21% higher rate in 2026/27 | Neither | Qualifying activity with supportable management | The zero rate does not cover every activity or taxation elsewhere |
| Andorra | 10% general rate | Applicable deductions may lower the effective burden if conditions are met | General rate of 10% | Neither | Entrepreneur establishing genuine residence or operations | A registered company or residence permit alone does not settle tax residence |
| Guernsey | 0% standard company rate | 10% or 20% can apply according to the income and activity | Resident liability depends on the applicable rules and allowances | Neither | Appropriate international business or investment structure | Activity classification and substance must be checked |
| Jersey | 0% standard company rate | 10% for certain financial services; higher rates for specified property, utility and retail activity; Pillar Two for in-scope groups | Standard rate of 20%, subject to the applicable allowances and calculation | Neither | Structure whose activity fits a confirmed rate category | “Jersey company” does not establish a zero-tax outcome |
| Ireland | 12.5% on trading income | Other income differs; Pillar Two can bring in-scope large groups to a 15% jurisdictional minimum effective rate | 20% and 40% income tax bands; other charges may apply | EU | Substantial Irish trading operations | 12.5% is not a universal rate for all profits or groups |
| Monaco | Business-profits tax may apply according to activity, including certain businesses earning more than 25% of turnover outside Monaco | Primarily considered for an individual’s residence position, not as a blanket company exemption | Generally no Monaco personal income tax, subject to important individual exceptions and foreign-country rules | Neither | Individual able to establish genuine residence | Personal residence does not automatically change company taxation |
Please note that the information provided in the above table is an initial reference guide only and should be verified with relevant tax authorities. This includes information on projected increases for 2026 in Cyprus, a standard rate of 15% in Gibraltar, the headline rate with any relevant refunds in Malta, and the ‘trading rate’ compared to the minimum tax rate for large groups in Ireland.
Switzerland
Switzerland is a hot spot of talent and culture with a lot of great places to live. As a location for businesses and entrepreneurs alike, Switzerland is very attractive. Important to note when talking about taxation, though, are the different levels of taxation (local, national).
Corporate taxation: Includes the federal tax, cantonal tax, and municipal tax on a corporation. This type of income tax consists of several components for both federal and corporate tax and varies from Canton to Municipality. Because of recent legislation, most benefits for principal companies and certain holding companies will cease to exist.
Personal taxation: Determined by the place of residence of the taxpayer. In addition to income from employment, the same tax rates apply to income from capital of residents and non-residents alike. Depending on the total assets held by a taxpayer as well as any applicable tax treaties, different tax rates apply.
International structures and substance. A registered office in Switzerland does not automatically trigger taxation of a company within Switzerland. Substance in Switzerland (i.e., registered office) must be distinguished from the tax entity and related tax obligations. As examples, the principal place of business, key management, main employees, and main revenues abroad would trigger taxation of a so-called holding within Switzerland.
Compliance and transparency. As mentioned earlier, a company set up in Switzerland needs to observe the due compliance with the required documentation for all its business activities and file tax returns on time. Additionally, disclosure statements regarding beneficial ownership for proposed entities or accounts (trusts, foundations, companies, etc.) need to be submitted to the relevant authorities as required by law, and such information would also need to be disclosed to other countries where such entities may open accounts.
Best suited for: Establishing a successful business with significant operational presence in Switzerland or for individuals who wish to relocate abroad for legitimate reasons.
Main limitations and risks: The Swiss tax system cannot be viewed uniformly from a taxation perspective. This especially refers to effective corporate tax rates in the various locations as well as to income tax and capital gains tax rates for earned income and for capital gains on a country and on a municipal level.
Practical takeaway: On a practical basis there is no universality of tax benefits of a corporate tax nature to establishments of a business in Switzerland. Benefits will typically be tied to specific businesses and/or owners on a cantonal/municipality-by-municipality basis.
Gibraltar
Gibraltar is included on this page for a variety of reasons, including the unique tax regime that Gibraltar operates, to provide a useful and advantageous jurisdiction for companies to set up and maintain a trading presence in the region.
Corporate taxation: The rate of corporate taxation in Gibraltar increases to 15% from 12.5% from July 1st, 2024. See the Government of Gibraltar website for details on corporate taxation. Again, here, the mere presence of foreign shareholders or non-resident directors does not automatically exempt all income from taxation in Gibraltar. Again, all income, whether from within Gibraltar or elsewhere in the world, is exempt from taxation only if the income originates from and is derived as a result of certain activities carried out within Gibraltar from which the income is sourced.
Personal taxation: Personal taxation of individuals resident in Gibraltar will also differ from the taxation of their companies resident in Gibraltar and must be separately considered.
International structures and substance: It is essential to have proper records of where contractual negotiations take place and decisions are made as well as records of employees that work in Gibraltar from elsewhere. This is of greater significance than a company being ‘non-resident.’
Compliance and transparency: Those registering a company within the Territory need to ensure full compliance with regard to its accounting and tax entries as well as any documentation (with strict time limits) required to register the company, such as for confirmation of the beneficial owners (natural and legal) and industry-specific licenses and/or reporting requirements where applicable.
Best suited for: Businesses with genuine employees and operations in Gibraltar under a Gibraltar structure.
Main limitations and risks: The scope of certain types of income NOT being subject to company tax exemptions and consequences in other countries where those same activities may be taxed.
Practical takeaway: For those thinking of opening up a business in Gibraltar, it is important to note that in considering the most suitable structure to accommodate proposed income and objectives, the foreign ownership of shareholders and/or directors alone does not guarantee zero tax for all income of a business in Gibraltar.
United Kingdom
This jurisdiction has been included for purposes of comparison for clients with customers, employees, or management based in the UK. As a general rule, the UK is not classified as a low-tax jurisdiction for normal trading companies.
Corporate taxation: Corporate tax rates have been reduced to 25% for all non-ring-fenced profits of a company for accounting periods that commence on or after 1 April 2023. For example, smaller trading companies with trading profits within maximum thresholds are charged at 19% and receive marginal relief where profits exceed these maximum thresholds. In addition, the chargeable gains from capital assets are taxed at 10%. The corporation tax rate therefore forms part of a company’s overall tax liability.
Personal taxation: As noted above, the tax liabilities of a company’s owners are completely separate from that of the company itself. UK resident traders will be required to pay income tax on all of the dividends they receive from their trading company and also on the salary they pay themselves via the company. In addition, they will also have to pay National Insurance contributions on the salary they pay themselves.
International Structures and Substance: Whilst setting up an overseas company for customers, employees, and management can have numerous benefits, registration in many countries is compulsorily required and indeed subsequently reported to HMRC. Moreover, the overseas trading company will be required to account for and pay tax in overseas countries (as well as face the tax charged within the UK) and even be subject to tax within the UK itself on its worldwide profits whilst a trading company.
Compliance and transparency: Matters relating to the reporting of information in respect of any person and filing of tax returns, etc., together with ongoing disclosures as to key individuals who are involved in a company, whether as directors or otherwise, and who control it or influence it.
Best Suited For: Trading companies resident in the UK. A separate legal entity for business operations is provided for the owners of the company.
Main limitations and risks: The main limitation for a UK trading company of this nature is the overall amount of taxes paid within a trading company. This is the corporate tax rate plus personal taxation rates plus National Insurance Contributions on behalf of all owners of the shares of the company, including all employees of the company.
Practical takeaway: It is important to note the difference between the company tax rate and the total taxes of the company’s owners, as well as their personal income tax plus National Insurance contributions on their share of company profits (including salary paid to employees). Foreign businesses trading in the UK have tax obligations in this country as well.
Scottish Limited Partnerships
A Scottish Limited Partnership (LP) – sometimes referred to as an SLP – is a recognized and legitimate partnership structure available within the UK. It is commonly used for joint ventures, trading, and investment structures and must not be confused with the illicit tax haven structures that have received recent publicity.
Corporate taxation: As an LP is treated as a ‘transparent’ entity in respect of its tax status, then from a corporate taxation perspective the LP is not a ‘zero corporation tax company. ‘ In general, all of an LP’s activities will be subject to UK taxation of a corporate nature in respect of companies who are partners.
Personal taxation: Personal taxation of shares is held by individual partners in their individual capacity; therefore, any gains on those shares will be subject to individual taxation. Any gains on shares held by a corporate partner will be subject to the normal corporate taxation rules of that company.
International structures and substance: As with all LPs, it is essential to establish the underlying structures of international LPs and their substance, i.e., the general partners and places of business. In terms of incorporating an LP within a Scottish framework, business can be conducted from anywhere in the world, and a review of both foreign and UK structures is advisable.
Compliance and transparency: A Scottish LP must comply with persons with significant control requirements of a Scottish limited company and also register for and submit ongoing accounts information.
Best suited for: This vehicle is suitable for establishing a legitimate partnership, with all the associated tax implications, at a level of individual partners.
Main limitations and risks: When establishing an LP, a number of restrictions apply, meaning all partners, including individual partners, will be taxed on their share of the partnership’s taxable profits. This means that there is no anonymity in respect of tax.
Practical takeaway: By forming an LP structure, a number of legitimate aims can be met, and, in some cases, a partnership structure may be more suitable than forming a corporation to trade or invest. However, it is worth noting that many ‘in_corp. & pay zero tax’ promotions incorrectly state that the LP structure also results in zero tax from incorporation. Great care must be taken to consider the taxation of each partner on their share of profits in an LP structure.
Serbia
The functioning of a business in Serbia requires employing local staff and conducting trade activities within the country.
Corporate taxation: A corporation would enjoy the tax rate of 15% and possibly qualify for some of the investment and research incentives, although such incentives are based on certain criteria and thus do not necessarily guarantee their granting.
Personal taxation: Also for the income of employees, the income tax and the obligatory contributions have to be calculated separately from the corporate taxation of the owner. Depending on the foreign ownership of the company, specific tax implications might occur for the company owner.
International structures and substance: A Serbian company set up and operated within the country with local staff and management is different from an overseas structure set up abroad and managed from abroad with all functions determined from overseas, such as cross-border services, finance, etc., each to be assessed on a case-by-case basis.
Compliance and transparency: The issues affect accounting, corporate tax returns on profits, payments of salaries, and payments of VAT, as well as required withholdings. All submissions are to be done electronically through the Tax Administration of Serbia.
Best suited for: Running a business in Serbia — yes. Set up an operation in Serbia as a tax-saving exercise — no.
Main limitations and risks: This 15% rate must be compared to the full cost to a business of employing staff and running other aspects of a business. Also, the tax implications for foreign owners of the business need to be considered.
Practical takeaway: Develop a detailed business plan with all employee-related costs included in the plan. Compare the after-tax cash return to the owner from the proposed business with that which could be earned with the same amount of capital in the owner’s home country. Note that country-specific incentives will likely not qualify to be included in formal forecasts prepared for third parties.
Malta
As an EU member state, Malta has been included in the analysis with reference to certain payments of shareholder refunds within a well-established international group structure being subject to specific considerations.
Corporate taxation: In Malta the corporate tax rate is set at 35% plus local taxes. Dividend distributions by a corporation can give rise to a refund of taxes actually paid by the corporation in full or in part, depending on the amount of the corporation’s assessable income and the number of qualifying shares held by the claiming shareholder(s).
Personal taxation: An individual’s status as resident and/or domicile can have a significant impact on their tax liability to Malta in respect of income distributed by non-Maltese companies as dividends.
International structures and substance: We examine if the tax structure is set up correctly to reflect the declared tax position or commercial circumstances. That would also include foreign-managed situations on a case-by-case basis.
Compliance and transparency: A Maltese company needs to maintain sufficient evidence with respect to its activities and its financial affairs (e.g. accounts, tax returns). In particular, sufficient evidence is required with respect to shareholders who are claiming a tax refund, and this must include full details of all such shareholders and supporting documentation where applicable.
Best suited for: This structure is most suitable for companies in the process of setting up a tax planning structure and generating qualifying profits and distributions prior to incorporation.
Main limitations and risks: Initially the corporate tax is paid in full by the company. Subsequently, any refund of corporate taxes distributed as a return of share capital is declared in the personal tax return of the ultimate shareholder(s), potentially subjecting the return of share capital to additional tax on dividend receipts from foreign corporate entities.
Practical takeaway: When establishing a tax planning structure, one needs to (i) ascertain (i) the total amount of corporate taxes paid and timing thereof (i.e., total corporate taxes paid minus the amount of refunds claimed and actually received by the Company at the relevant time plus any timing issues therein); (ii) assess the personal tax implications of the ultimate Shareholder(s) thereon and the likely exaggeration thereof over the corporate tax rate paid by the Company in the first place.
Luxembourg
Luxembourg has more to offer bigger holding and investment structures, whereas for smaller trading companies there may be no significant advantages over similar structures in other countries, since the tax savings in Luxembourg will not be sufficient to offset the corporate tax, as well as municipal business tax and other taxes, of the holding.
Corporate taxation: Income from a corporation is subject to the corporate income tax as well as to municipal business tax and other taxes that the taxpayer must pay. In case of a holding, a participation exemption may be granted depending on the type of investment and the specific transaction.
Personal taxation: Salaries and dividends, as well as other forms of capital income, are subject to income tax, which is usually paid by the individual. No benefits from a holding can be assumed when distributing income to its owner.
International structures and substance: The decisions on financing and investments can be made by others within the group provided that such an arrangement is established in a serious and commercially reasonable manner. The holding company or investment company can be managed by a management board or supervisory board.
Compliance and transparency: As for corporate tax and municipal business tax, accounting records have to be kept and reports have to be submitted. In addition, a holding company has to register its shareholders or owners, and it may be subject to particular requirements depending on the specific nature of its investments.
Best suited for: Holding or investment structures that are able to cover the costs of a corporation (corporate tax and municipal business tax and others).
Main limitations and risks: The benefit of participation exemption may not be granted for all holdings and for all disposals. In addition, the structural costs (i.e., corporate tax and municipal business tax, etc.) of such a corporate form are likely to exceed any potential savings for small portfolios.
Practical takeaway: Model the income into the Luxembourg entity, model the asset sale from the Luxembourg entity, and then model the ultimate distribution of cash to the owner of the holding entity structure against a simple holding structure.
Cyprus
All legitimate EU business activities, holding operations, or even personal relocation to Cyprus can be considered.
Corporate taxation: Effective 1st of January 2026, corporate income is subject to 15% tax. The reliefs due for different categories of income shall be reviewed and assessed individually. For information purposes only, the previous general tax rate of 12.5% is stated on this website.
Personal taxation: The above information shall be updated in detail in order to determine all of the various factors that may affect Cyprus of worldwide income deriving from salary, distributions, and capital gains, and in which other countries an individual may also remain a tax resident.
International structures and substance: When setting up an international structure, the amount of substance required to be established in the jurisdiction in which the company is incorporated has to be reviewed. Even if a Cyprus company is incorporated and managed from abroad, there is no guarantee that the expected benefits will be achieved.
Compliance and transparency: All the required accounting documents, tax returns, annual reports, and other disclosure documents, such as the information on the shareholding, are clearly listed.
Best suited for: This type of corporate structure is ideal for business owners and established companies with sufficient assets and viable business activities that can sustainfully support the appropriate Holding / Operational structure in Cyprus.
Main limitations and risks: Although the low headline rate does no longer apply, there are significant differences between the tax residence status of a company and that of its owners. These differences could be very adverse for the foreign owners of a Cypriot company.
Practical takeaway: An operational or holding structure in Cyprus is best suited for owners or businesses that have substantial assets and real activities in Cyprus to support such a structure. The company and the owners will be considered as one unit in assessing the advantages of having an operational or holding structure in Cyprus. Thus, the division of decisions, i.e., who decides what, and the responsibilities assigned prior to the incorporation of a company are crucial in order to determine what advantages will apply to the income of the company.
Isle of Man
The Isle of Man has been a favored location for a wide range of organizations due to its zero corporate tax rate. Yet as with any number of other locations with favorable tax regimes, there are significant exceptions and limitations to the Isle of Man’s corporate tax environment as well as the way in which various types of income are taxed.
Corporate taxation: Sector-specific rates of corporation tax apply for certain trading activities, such as banking or retailing. In addition, the standard rate of corporate tax applies. From April 2023, all companies resident in the Isle of Man are subject to a minimum top-up tax under the Island’s Pillar Two regime of 15% on their relevant profits.
Personal taxation: Personal taxation for residents in the Isle of Man for the fiscal year 2026/27 is to be taxed at 10% up to a certain threshold, with the remainder being taxed at 21% on that excess. Worldwide income of residents will need to be declared and appropriate relief claimed on their annual tax returns where applicable.
International structures and substance: Whether the company is controlled abroad and satisfies the Isle of Man economic substance test.
Compliance and transparency: Reporting compliance and transparency for companies with operations in the Isle of Man requires them to disclose their zero rate of tax on their tax returns. In addition, various categories of trade are currently under scrutiny to establish whether sufficient substance is conducted on the island from a tax avoidance perspective. For larger groups with operations on the island, additional reporting requirements in relation to minimum tax liabilities have recently been imposed.
Best suited for: Organizations are best suited to sit these structures in the Isle of Man in order to ensure sufficient management substance within the very thriving financial center.
Main limitations and risks: There are several limitations and risks associated with the Isle of Man’s 0% corporation tax rate. The zero rate does not apply to all types of income, and cross-border aspects (e.g., income of non-resident owners) are subject to taxation.
Practical takeaway: Importantly, these points need to be included in a forecast of all types of income that the company may generate and a separate assessment made of foreign management and of ownership by non-residents, and of capital gains treatment with a subsequent evaluation of the substance required to be conducted and the minimum tax obligations of the Isle of Man.
Andorra
A dynamic and compact country with lots of opportunities to start and grow a business while living in Andorra.
Corporate taxation: The nominal corporate tax rate in Andorra is 10% (plus potential for additional tax deductions in certain situations).
Personal taxation: Resident individuals are subject to a personal income tax rate of 10% on their worldwide income provided that the amount of tax so calculated is greater than the amount of tax due in any other country and, where appropriate, on profits from Andorran sources.
International structures and substance: Foreign incorporated companies owned by resident individuals in Andorra are cross-border structuring vehicles. We will examine how foreign-owned entities are managed and incorporated in Andorra from a cross-border perspective and regulated whilst operating from Andorra.
Compliance and transparency: Registered entities must maintain adequate and accurate accounting records that detail all of their business activities within Andorra and worldwide and enable an accurate assessment to be made of their annual profits to determine their tax liability as appropriate and in compliance with any relevant indirect taxes.
Best suited for: Owner-managed businesses and their proprietors who plan to relocate to Andorra to establish and operate their enterprises from there.
Main limitations and risks: The fact that permits of residency for individuals, registration of companies, and taxation of residents’ income are all separate matters that have to be analyzed in turn may bring disappointment to individuals who are taxpayers in other countries and who hope to continue working there while at the same time enjoying Andorra’s 10% rate of tax for corporate profits.
Practical takeaway: The key point to note when comparing 10% taxation in Andorra against higher tax rates in other countries is the amount of time you plan to spend in Andorra versus your home country.
Guernsey
This Corporate Tax Guide covers the Guernsey corporate framework relevant to international businesses or investment structures set up in Guernsey conducting business within Guernsey from time to time.
Corporate taxation: Tax rates for companies in Guernsey are typically 0% for trades; however, there are exceptions where certain types of income will incur an intermediate rate of 10% or a higher rate of 20% where conditions for higher rates are satisfied. A clear definition of income and proper categorization is necessary in order to determine if any of that income is subject to a 0% tax rate.
Personal taxation: Advice should also be given to employees regarding current income tax legislation and all available reliefs and rates applicable to them in their personal tax circumstances. This will involve reference to their total income from all sources for the relevant tax year and all distributions from zero-tax companies.
International structures and substance: As stated above, principal management activities and principal operations must be carried out within Guernsey for the structure in question.
Compliance and transparency: Annual Guernsey tax return plus company accounts for the relevant tax year, which includes confirmation of specified matters as set out in Guernsey tax regulations and sector-specific reporting requirements. Clear income classification, legitimate commercial activities, and full compliance with ongoing requirements are essential features that this solution can provide for a client.
Best suited for: Clear income classification; genuine commercial activity; capacity to comply with ongoing requirements.
Main limitations and risks: Despite a standard tax rate of 0%, there are many exceptions to this rule, such as certain trade tax type situations and a tax levied upon the overseas activities of the owners of a Guernsey company.
Practical takeaway: Distributions to resident individuals (regulated) in Guernsey are taxed. Income derived from foreign activities conducted by resident individuals who are also owners of the Guernsey company in question is subject to taxes, which are different from the 0% rate of the company itself. A written analysis of the taxes (including the applicable rates for each category of income of the company) and of the activities required to be conducted in Guernsey by these types of company structures in order to obtain favorable taxation in Guernsey would be a good starting point for this work and should not commence or concentrate solely at the end with the 0% rate of the company.
Jersey
Jersey is reviewed as a tax haven, and, whilst it has a zero standard rate of tax, there are a number of higher-rate activities with requirements to provide sufficient economic activity.
Corporate taxation: Additional information on corporate taxation can be found on the Jersey Government website. Corporate entities conducting regulated financial services activities are subject to a 10% tax on their profits. Property, utility, and retail activities have higher tax rates of up to 20%, depending on the circumstances of the company. In addition, Jersey’s approach to Pillar Two taxation of large groups of companies will also need to be considered.
Personal taxation: The Jersey resident personal tax rate is 20% plus the sum of various income allowances less the total of all income actually received from all sources. Note this rate only applies to Jersey residents – non-residents must check the tax due in their country of residence.
International structures and substance: Companies in Jersey must demonstrate economic substance with respect to the proposed management functions of the company and whether those management functions will meet the objectives of generating income from the company’s activities and associated costs.
Compliance and transparency: As tax returns, accounts showing economic activities and their associated costs to derive profits for each activity must be submitted by companies within Jersey; resident companies are also required to prepare annual financial statements, which must be prepared in accordance with an appropriate reporting standard. Beneficial ownership information must also be accurate and updated on an ongoing basis.
Best suited for: Jersey forms a good tax haven for fixed-rate category businesses that can demonstrate suitable management to meet the requirements of Jersey law.
Main limitations and risks: The limitations of Jersey as a tax haven with a zero standard rate of tax and also the potential for extra taxes to be imposed on individual owners or groups of owners collectively.
Practical takeaway: A key point to note in relation to Jersey is the classification of activities and ensuring that the company in question has appropriate economic substance and adequate costs to the company to enable appropriate taxation of such distributions in Jersey.
Ireland
Ireland can offer excellent trading operations within the EU if suitable staff and management can be established within Ireland.
Corporate taxation: The corporate tax rate for a trading company’s trading income from a trading company is 12.5%, as mentioned above. All other gains will be taxed under different terms, and in addition, trading income from companies within a group of companies that are subject to Pillar Two will incur a further top-up tax rate of at least 15%, as noted above. This needs to be modeled for all corporate gains in order to ascertain the correct tax for any given circumstance.
Personal taxation: Personal taxation of owners of shares in trading companies will be subject to dividend withholding tax. Relief exists in certain cases, and an exemption may also apply where sufficient substance is demonstrated within the trading company.
International structures and substance: A company incorporated in Ireland is a tax resident in accordance with company formation rules for that country. For a trading operation, remote offices, intellectual property, and staff functions must be located where the business asserts they are.
Compliance and transparency: Payment of stamp duties, filing returns on time, and accounting with due care. Registration of ultimate beneficial owner(s). Large corporate groups will register for Pillar Two compliance in Ireland and submit annual returns in respect thereof.
Best suited for: This location would be best suited for companies involved in substantial trading activities within Ireland.
Main limitations and risks: The 12.5% rate does not apply universally (owner’s taxes, distribution withholding taxes, etc.); large group regimes, etc., will impact the effective tax rate within a trading structure.
Practical takeaway: Owner’s taxes, distribution withholding taxes, large group regimes, etc. will influence the effective tax rate for trade, and therefore it is very important to provide full assessments, models, and sensible forecasts of potential tax burdens.
Monaco
The tax treatment of personal issues in relation to relocation to Monaco should be treated separately from corporate tax issues.
Corporate taxation: Monaco is subject to a business profits tax (OTT) on the industrial or commercial activities of a company that is based in Monaco. However, OTT only needs to be paid by companies whose more than 25% of turnover is derived from activities outside of Monaco performed by the same Monaco company. Many people wrongly believe that all companies registered in Monaco are totally tax exempt.
Personal taxation: The challenge of determining the tax status of relocated individuals while analyzing the elements that could consider an individual a tax resident in Monaco, taking into account his nationality and any additional factors that could also consider him a tax resident in other countries.
International structures: As opposed to the above situation of an individual moving to Monaco whilst operating his/her business from elsewhere in the world, an international structure refers to and is different from a corporation that has already been incorporated in Monaco and whose tax status needs to be ascertained.
Compliance and transparency: Ensure proper copies of residence documentation of the individual, registration of the company, business licenses and other compliance requirements, and accounting and financial reporting by the individual, as well as bank account opening for the company.
Best suited for: This structure is suitable for individuals who relocate to Monaco on a full-time basis and require a structure for the effective management of assets, income, and business interests whilst resident in the country.
Main limitations and risks: Corporate profits generated in Monaco by a company incorporated in this country might be subject to business profits tax. However, criteria applied by other countries to their residents for taxation purposes may be different.
Practical takeaway: One needs to assess the tax implications of an individual’s residency in Monaco prior to looking at the potential tax benefits that a company may have when it is established or relocated to Monaco.
Headline Tax Rate vs. Effective Tax Burden
The rate of corporate tax has been set by government for the taxable profits of all companies. Importantly, the tax rate of a company is not a comparable figure with the after-income tax distribution from a trust structure.
- Tax on the company’s trading or investment profits;
- Tax on overseas income, including withholding tax on cross-border payments;
- Tax on dividends or salary disbursed to the owner;
- Payroll taxes and social contributions;
- The implications of controlled foreign company regulations;
- Tax on permanent establishments abroad managed from that location.
- Transfer pricing and anti-abuse provisions;
- Staff costs, office expenses, and other allowable expenditures.
- Pillar Two: if a large group falls within its scope.
For example, a consultant living in a country (home country) can set up a zero-rated company in his country of tax residence (for example, incorporation of a company). It usually takes several months to get a certificate of incorporation. The consultant may then realize that setting up a zero-rated company in a foreign country is not enough to fulfill all tax compliance requirements in his home country.
Which Jurisdiction Fits Which Use Case?
When choosing the most suitable international service entity for our clients, we consider various factors, including the kind of work that is going to be conducted, where they conduct their operations from, and the nationality of the owner(s). The following are examples:
- International services or consulting: First, you identify all locations where you will render services and where the key decisions will be taken. Then you research the corporate tax rates plus the applicable VAT and other sales taxes of a country. You research all options for compensating the owner of an international entity, the distribution of dividends, and any annual fees that have to be paid to a foreign entity, e.g., to a lawyer who has incorporated the foreign entity for you. A country with low tax rates is not necessarily the best option when the owner is also taxable in his home country.
- SaaS or technology company: For a SaaS or technology company, the fair rate depends on the location of the developers and the management. Who is generating the intellectual property for your company? Where are your customers and your employees? Countries like Ireland, Cyprus, and Switzerland have to be looked at closely, as there are considerable benefits attributed to IP generated within a company incorporated in these countries.
- Holding company: It’s also important to clarify the tax implications on the distribution of capital gains from sales of assets owned by the holding company (such as shares, units in tradeable trustee companies, property, etc.). Also important is to establish the ‘practicalities’ and ‘operational costs’ of such structures to establish whether or not they are ‘effective.’
- Investor or high-net-worth individual: In seeking to get the best return on their investments, the investor or high-net-worth individual can easily be misled by the media into believing that a flight to Switzerland, Monaco, Jersey, or Guernsey will automatically result in their company paying the lowest corporate tax rate in the world. Each country has its own set of complex idiosyncrasies that cannot be covered by a travel guide.
- Digital entrepreneur relocating personally: It is often unclear when a digital entrepreneur moves personally to a new location whether he will become a tax resident there. This might differ from the corporate tax rate of the location where the entrepreneur’s businesses are based to carry out and to fulfill obligations as an entrepreneur (e.g. Andorra, Cyprus, Isle of Man). The company may be taxed differently from its owner.
- Large multinational group: The above points need to be looked at in detail in conjunction with information exchange agreements in place and the respective tax authority’s interpretation of the Pillar Two proposals on transfer pricing and associated information filing requirements. Even in countries with lower domestic tax rates, such as 12.5% or even 0%, the group’s effective tax rate could well end up higher than the nominal tax rate charged in the country in question.
When a Low-Tax Jurisdiction May Not Save You Tax
The owner of the reorganization structure will be taxed in his/her home country, and even if some tax savings are anticipated in the low-tax jurisdiction, these will most likely not be realized in full. The profits of a Controlled Foreign Corporation (CFC) are usually distributed to the owner(s) of the CFC (or the parent company of the CFC is based in the owner’s country of residence). The main decisions with regard to the low tax structure can be taken from any place in the world. A permanent establishment of the company can be declared with reference to the personnel involved and their activities within the context of the newly established structure. However, it is unclear whether the tax benefits will be fulfilled with this new structure.
In addition to the savings from reorganization, it is also important to take into account the withholding tax and other additional taxes on salary and dividend payments, mandatory local expenses, and the minimum top-up taxes for certain taxpayer groups and structures. Also, other costs of alternative structures need to be taken into account.
Compliance, Substance and Transparency
Establishing a corporation in a low-tax jurisdiction requires more than just minimum administrative efforts to complete the incorporation process. Corporations and foundations also need to meet several obligations, such as preparing annual accounts and tax returns and facing audits. Additionally, beneficial ownership requirements must be met, and companies must hold payroll records, be able to prove their substance, and possibly obtain a license to conduct business in a jurisdiction.
So-called “substance” refers to more than a registered office for a company established in a low-tax jurisdiction. It refers to persons who manage the company, who conduct the main business activities of the company, and who also take on corresponding risks. The term “substance” and the costs necessary to establish it vary from country to country and from one regulatory authority to another.
How to Choose a Jurisdiction: Checklist
- Identify all countries where the owners, directors, employees, assets, and business operations are based.
- Is the income of the business mainly trading income, or is it made up of other types of income (for example: investment income, property income, etc.), and are there any restrictions on this type of income.
- Current tax rates and regulations for different types of income to review.
- Assess how the new company will be managed in all the relevant jurisdictions; as a permanent establishment in those and possibly other countries, and as a CFC (Subject Foreign Company) for tax purposes in other countries.
- Calculate total tax liabilities of the owner for salary, dividends, and capital gains.
- Examine the withholding tax implications arising from payments made by and to the company.
- Some countries also need documentation in order to grant relief or an exemption.
- Assess costs for local management, premises, personnel, and accounting services in the selected jurisdiction.
- Compare your detailed projections against your existing arrangements.
- Consult with local tax experts in all relevant jurisdictions to finalize the corporate structure.
Conclusion
Many factors must be considered when selecting a new jurisdiction, including the regulatory environment and the aggregate cost of tax and compliance plus operating expenses in that jurisdiction compared to your current structure, and that even low headline tax rates are not sufficient to be considered on their own.
Start with the owner’s residence, the location of management and staff, the nature of income, and the distribution of profits to the owner. Offshore Pro Group will then organize this for you and assess the most suitable corporate structure. We will highlight potential issues that require jurisdiction-specific tax advice before registering the company.
FAQs
Are European tax havens legal?
Setting up a company in a tax haven or moving to a low-tax country as a tax resident is permissible. However, the owner of a company as well as the company itself has to comply with the respective tax reporting requirements of the countries involved.
Does a 0% corporate tax rate mean I will pay no tax?
It is important to recognize that a 0% tax rate for a corporate entity does not mean there will be no taxes to pay. Income tax, capital gains tax, sales tax, and Value Added Tax (VAT), as well as Social Security contributions, are examples of additional taxes that may need to be paid.
Do I have to live in the jurisdiction?
As a rule, residency for a company is different from that of its owner. As an example, the owner of a company in a foreign tax haven can reside in his home country. Whether managing a foreign company from home leads to it being treated as a resident in the owner’s home country for tax purposes is another matter, however.
Which jurisdiction is best for a small international business?
Key factors that small international businesses should consider when choosing a foreign jurisdiction to operate from are those that consider the potential cost of properly structuring a foreign entity to minimize future risk in comparison to the potential savings in corporate tax.
What is economic substance?
The term “economic substance” refers to real activities of full-time staff, genuine management decisions by directors and other officials,, and other expenses incurred by a company to establish economic activities within a foreign jurisdiction and to gain access to the regulatory framework of that jurisdiction. The formal requirements with respect to economic substance may vary from one jurisdiction to another.
Can I manage an offshore company from my home country?
Management of an offshore company from within a home country is possible but needs to be evaluated against the potential for such activity to have a tax impact within that country. Typically, tax on profits from a foreign incorporated company is determined by the location of the company and not by the location of management.
Are European low-tax jurisdictions anonymous?
No, anonymity is not provided by low-tax locations. For example, many of these locations require certain information to be disclosed in a corporate register. In addition, banks and financial services providers are subject to customer due diligence requirements and must exchange information regarding taxation in accordance with tax agreements.